Domenic Gallippi
Mortgage Agent Level 2 - M23007938
domenic@bettermortgagesbydom.ca
Tel: 416-801-6616 | Cell: 416-801-6616
Domenic Gallippi
Mortgage Agent Level 2 - M23007938
domenic@bettermortgagesbydom.ca
Tel: 416-801-6616 | Cell: 416-801-6616
There's something I've been thinking about lately when it comes to my role as a Mortgage Agent.
People generally come to me because they want to accomplish something.
They want to purchase a home, refinance an existing mortgage, consolidate debt, access equity or find a better deal when their mortgage comes up for renewal.
And naturally, they expect me to help them find a way to make it happen.
That's my job, after all.
But I've come to believe that one of the most important parts of my job is knowing when not to recommend a mortgage.
And sometimes, that's a much more difficult conversation to have.
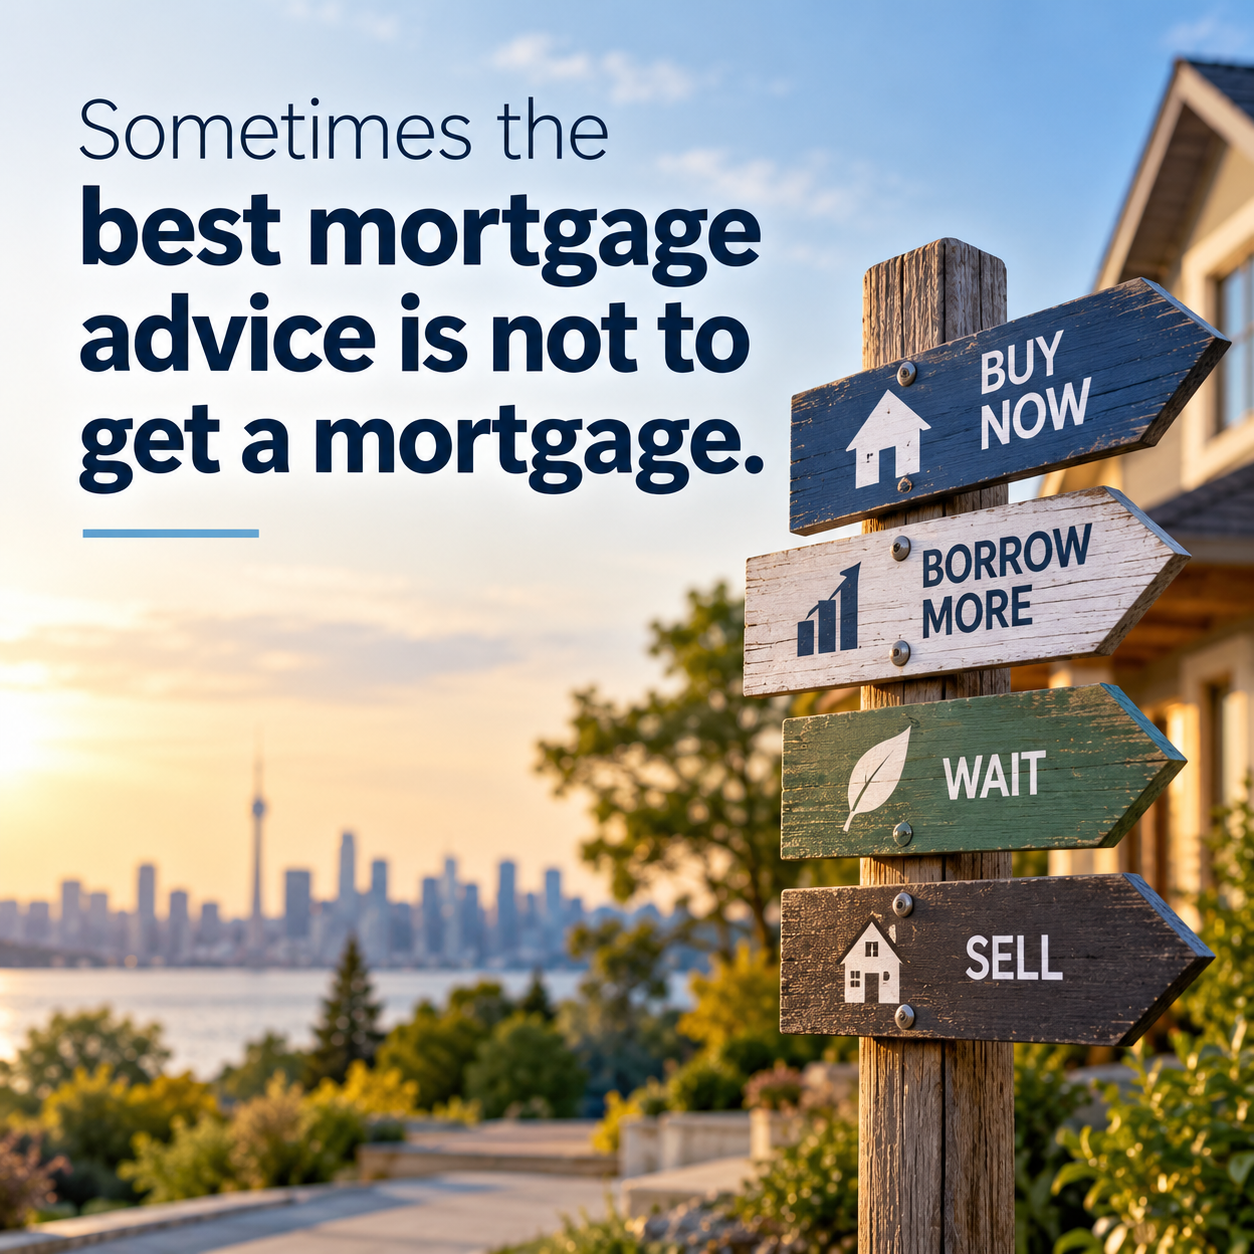
I've had conversations with clients where, after reviewing their circumstances, I've suggested that they reconsider purchasing a home right now.
Not because homeownership isn't a worthwhile goal.
And not because I couldn't necessarily find a lender willing to provide financing.
But because the timing, financial obligations or potential risks didn't make sense for their situation.
I've also had conversations with homeowners where I've suggested that selling their property might be a better long-term financial decision than continuing to borrow against it.
That's never an easy conversation.
People become emotionally attached to their homes. They've invested years of effort and money into them. And selling can feel like admitting defeat.
But sometimes, continuing to refinance or accumulate debt simply postpones a problem rather than solves it.
And postponing a financial problem can make it significantly more expensive to address later.
In fact, one homeowner I worked with ultimately made the difficult decision to sell after we had a very candid conversation about their financial situation. They were understandably reluctant at first, but they've since told me that life is calmer, the financial stress has eased considerably, and they're grateful I was willing to have that honest conversation with them. It's a reminder that sometimes the best financial outcome isn't the one we originally hoped for.
I don't believe I'm doing someone a favour by helping them take on more debt if I have serious concerns about their ability to manage it.
My job isn't to make every mortgage transaction happen. It's to help people make informed decisions about whether the transaction should happen in the first place.
Something that might surprise people is how often homeowners come to me even though they already have a mortgage with another lender - quite often one of the Big Banks.
Sometimes they're unhappy with the service they've received. Sometimes they feel like they don't really have a relationship with anyone at their bank who understands their circumstances. Other times, they're questioning whether they received the right advice in the first place, or whether the renewal offer sitting in front of them is genuinely competitive.
And I understand that frustration.
A mortgage is likely one of the largest financial obligations someone will ever take on. Yet it's not uncommon for homeowners to feel like they're just another account number, particularly when their mortgage comes up for renewal.
Often, what they're really looking for isn't necessarily a new lender.
They're looking for someone who will take the time to understand their situation, explain their options and give them confidence that they're making the right decision.
That's where I believe I can add value.
I regularly help homeowners review the renewal offers they receive from their existing lenders, compare those offers against alternatives available in the market, and understand the features, flexibility and potential costs associated with their options.
Sometimes we discover that another lender can provide a meaningfully better solution.
But other times, the existing lender's offer is already competitive - or can become competitive with a little negotiation.
In those situations, I may encourage the homeowner to go back to their lender, armed with a better understanding of the market and a clearer sense of what they should be asking for.
Because changing lenders isn't automatically beneficial.
There can be legal or administrative costs, qualification requirements, differences in mortgage features and other considerations that need to be weighed against the potential savings.
And if the existing lender is prepared to offer a competitive rate and suitable terms, switching may provide little or no meaningful benefit.
Sometimes the value I provide isn't in arranging a new mortgage. It's in helping someone have a better conversation with the lender they already have.
And if that conversation results in a better offer, a clearer understanding of their mortgage or simply greater confidence in their decision, I consider that a positive outcome.
Even if it means I don't earn a commission.
Because the objective should be to improve the client's financial position - not simply generate another mortgage transaction.
This is another issue I feel strongly about.
One of the questions borrowers sometimes ask is whether I can get them approved for more than another mortgage professional has suggested.
And sometimes the answer is ‘yes’.
Different lenders have different policies. Some offer more flexibility in how they assess income, rental properties, self-employment or existing obligations.
An experienced Mortgage Agent who understands these differences may be able to identify legitimate financing options that weren't previously considered.
That's part of the value we bring.
But I would encourage anyone to be cautious if they're suddenly being offered a substantially larger mortgage approval without a clear explanation of why.
More borrowing power is not automatically a better financial outcome.
There are really two questions that need to be answered:
Will a lender approve this mortgage?
And perhaps more importantly:
Can you comfortably manage this mortgage while still meeting your other financial obligations and goals?
Those aren't always the same thing.
A lender's maximum approval is based on its underwriting policies and assessment of risk.
It isn't necessarily a recommendation about how much debt you should personally take on.
Your financial life involves more than mortgage payments.
There are property taxes, utilities, maintenance costs, groceries, transportation, family expenses, savings, retirement planning and unexpected events.
A mortgage that technically meets a lender's qualification criteria can still leave a household with very little financial flexibility.
And that should be part of the conversation before anyone commits to borrowing.
There's another side to this that I think consumers should understand.
Not all mortgage approvals are created equal.
The vast majority of mortgage professionals work hard to arrange legitimate financing for their clients.
And a higher approval amount doesn't, by itself, mean anything improper has occurred.
But borrowers should understand how their applications are being presented to lenders.
The income, employment, debts, down payment and other financial information used to support an application need to be accurate and verifiable.
If someone suggests changing or overstating information to obtain a larger approval, that's a serious warning sign.
It may seem like a shortcut to achieving homeownership.
But the consequences can be significant.
A lender may identify inconsistencies before closing and withdraw its approval, potentially leaving a purchaser unable to complete a transaction.
Problems may also emerge later if a borrower struggles with payments on a mortgage that was never genuinely affordable.
And inaccurate information discovered during a future application, renewal review or refinancing process can create further difficulties.
The point isn't to frighten people.
It's to encourage them to ask questions and understand the financing being arranged on their behalf.
You should never feel that you need to misrepresent your financial circumstances to become a homeowner.
A sound mortgage strategy should be built around your actual financial position - not a version of it created to satisfy an approval requirement.
I've spent more than 30 years working in financial services, including roles involving lending strategy, mortgage products and the development of mortgage financing solutions.
That experience has shaped how I approach my work today.
I don't look at a mortgage as an isolated transaction.
I look at how it fits into someone's broader financial circumstances.
What are they trying to accomplish?
What does their income look like today, and how stable is it?
How much flexibility will they have after making their mortgage payment?
What happens if interest rates change, their income is interrupted or an unexpected expense arises?
Are there alternatives that could accomplish the same objective with less risk or lower cost?
And sometimes the most important question is:
Is this really the right financial decision for them?
I don't always have an easy answer.
And I certainly don't pretend to know every aspect of someone's life better than they do.
But I do believe I owe clients an informed assessment, a clear explanation of their options and the willingness to raise concerns when I see them.
Even when those concerns aren't what they were hoping to hear.
I want to be clear about something.
I'm running a business.
Like other Mortgage Agents, I earn income from arranging mortgage transactions.
And of course, I want my business to succeed.
There's nothing wrong with that.
But I don't believe my financial interests should determine the advice I give.
If a client would be better served by staying with their current lender, waiting before purchasing, borrowing less - or even selling their home rather than continuing to refinance - I need to be willing to say so.
That doesn't make me a saint.
It simply reflects how I believe this business should work.
Because the consequences of a mortgage decision can stay with a household for years.
The commission earned on a transaction is temporary.
The financial obligations taken on by the borrower are not.
And ultimately, it's the borrower who has to live with those decisions.
If there's one message I'd like people to take away from this, it's that choosing a Mortgage Agent should involve more than comparing interest rates or asking who can secure the largest approval.
Rates matter.
Lender access matters.
Experience and knowledge of mortgage programs matter.
But so does judgment.
So does transparency.
And so does having someone who's prepared to tell you something you might not want to hear.
A good mortgage conversation shouldn't always end with, "Here's how much you can borrow."
Sometimes it should end with, "Here's what I think you should consider before you borrow."
Or, "Let's see whether your current lender can do better."
Or even, "I'm not sure taking on more debt is the right answer for you."
I don't expect every client to agree with every recommendation I make.
Ultimately, the decision belongs to them.
But I want them to feel confident that the advice they're receiving is intended to help them make the best decision for their circumstances - not simply the decision that results in a mortgage transaction.
Because getting someone approved for a mortgage is one thing. Helping them make a decision they'll still feel good about years later is something else entirely.
And that's the kind of Mortgage Agent I strive to be.
Whether you're purchasing a home, renewing a mortgage, considering refinancing or simply wondering whether your current mortgage strategy still makes sense, I'm happy to help you work through your options.
Sometimes that means finding a better mortgage solution.
And sometimes it means discovering that the best next step isn't a new mortgage at all.
Either way, the conversation should start with what's right for you.