Domenic Gallippi
Mortgage Agent Level 2 - M23007938
domenic@bettermortgagesbydom.ca
Tel: 416-801-6616 | Cell: 416-801-6616
Domenic Gallippi
Mortgage Agent Level 2 - M23007938
domenic@bettermortgagesbydom.ca
Tel: 416-801-6616 | Cell: 416-801-6616
For many buyers in the Greater Toronto Area, affordability is one of the biggest challenges to homeownership.
But what if the property you purchased could also generate income?
A home with a legal basement apartment, a duplex or another small multi-unit property may offer an interesting opportunity.
You live in one portion of the property while renting another.
The rental income helps offset the cost of ownership and, in some cases, may help you qualify for the mortgage.
But there's an important distinction:
The amount of rent you expect to receive and the amount of rent a lender will recognize are not necessarily the same.
Understanding that difference before making an offer can be extremely valuable.
Imagine you're considering a home with a separate basement apartment.
The property has an asking price of $900,000, and the basement could generate $2,000 per month in rent.
That's potentially $24,000 in annual rental income.
From a household budgeting perspective, that income could make the monthly cost of homeownership considerably more manageable.
But lenders don't simply treat every dollar of rental income as additional employment income.
They need to account for the nature of the property, the reliability of the rent and the underwriting rules that apply.
This is where mortgage strategy becomes particularly important.
Lenders may use different methods for recognizing rental income.
Two common approaches are rental-income add-back and rental-income offset.
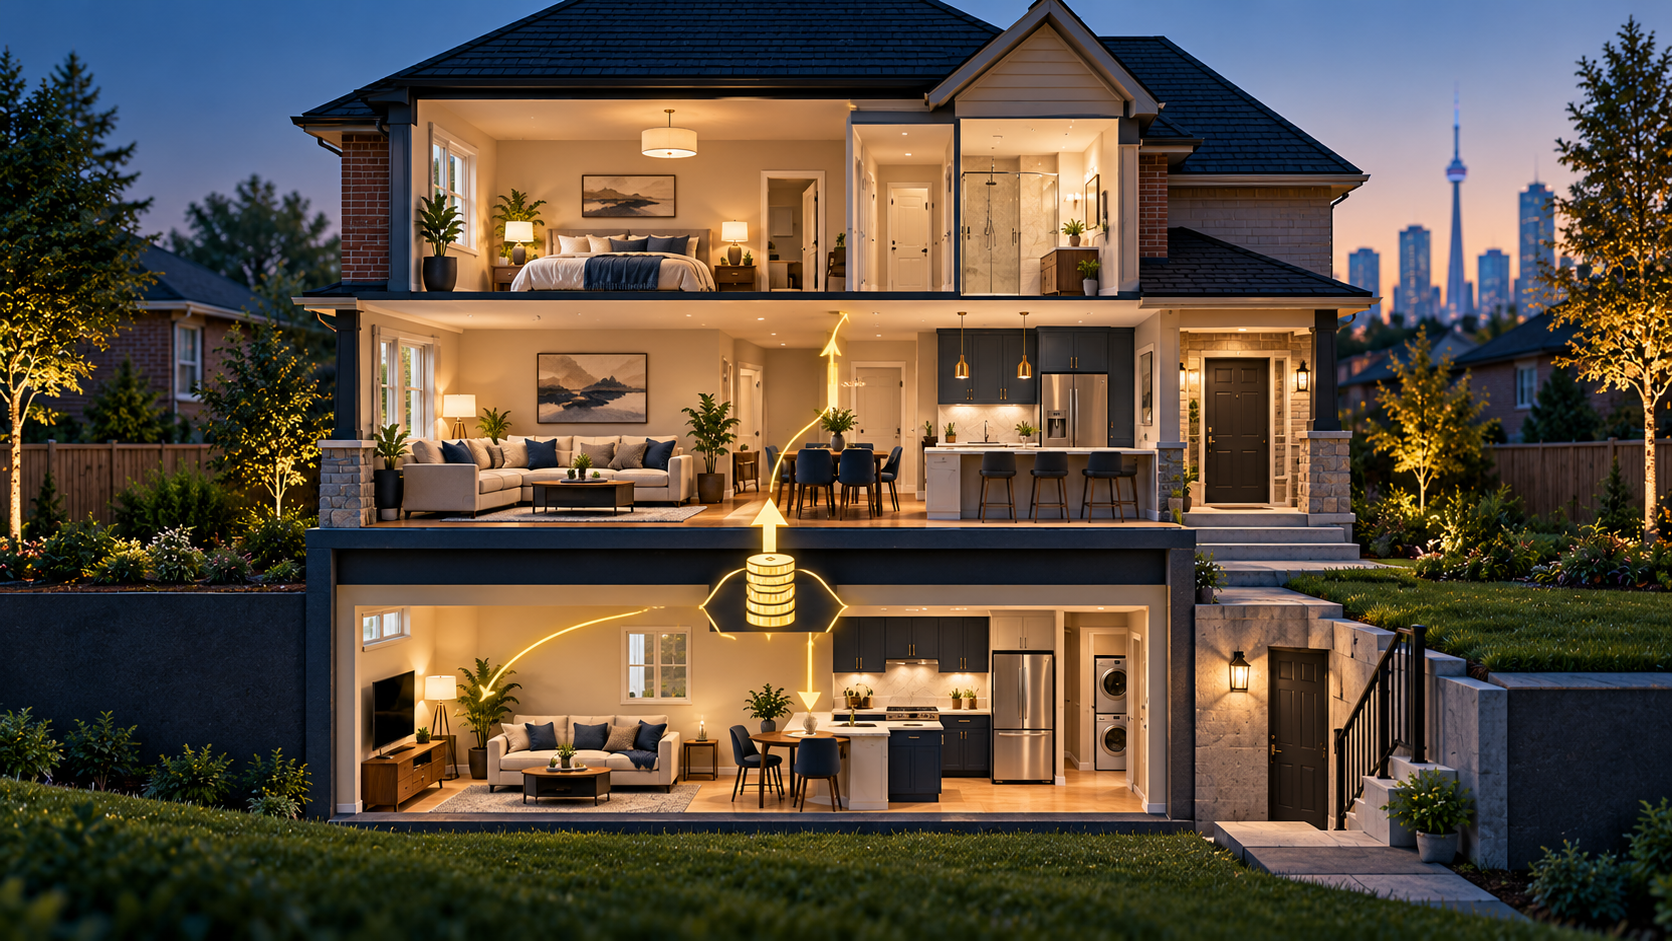
Under this approach, the lender recognizes an eligible portion of rental income as additional qualifying income.
For example, a lender that permits a 50% add-back of $2,000 monthly rent would recognize $1,000 per month, or $12,000 annually, under that methodology.
That doesn't necessarily mean the borrower receives a dollar-for-dollar increase in borrowing capacity. The lender still calculates the applicable debt-service ratios.
Under an offset approach, the lender may apply an eligible portion of the rent against certain property expenses when assessing qualification.
The exact calculation varies by lender and program.
The result can be quite different from the add-back approach, even when the borrower and property are identical.
For insured mortgages, CMHC also publishes specific rental-income methodologies. For example, qualifying rental income for an owner-occupied two-unit property that is the subject of the application may be assessed using up to 100% of gross rent under the applicable CMHC approach. That is a program-specific maximum, not a guarantee that every lender will accept all the rent.
This is one reason lender selection can be more important than simply finding the lowest advertised rate.
Does the rental unit need to be legal?
Property eligibility is another important consideration.
Lenders may review whether a rental unit is permitted under municipal requirements and whether the property meets their lending policies.
A finished basement with a kitchen and separate entrance isn't automatically a legal secondary dwelling unit.
Buyers should investigate zoning, building permits, fire safety, property configuration and insurance requirements.
The distinction matters because an attractive rental estimate is of limited value if the unit cannot lawfully be rented or does not meet the lender's requirements.
What if the basement isn't currently rented?
Suppose you're buying a home with a vacant basement apartment.
Can the lender still recognize rental income?
Potentially.
Some lenders may accept market rent supported by an appraisal or another approved assessment.
Others may require an existing lease or additional documentation.
The answer depends on the lender, property and financing program.
This is something I would want to establish before a buyer relies on rental income to qualify.
What about duplexes, triplexes and fourplexes?
The number of units can affect financing options.
For eligible owner-occupied properties under CMHC's homeowner insurance framework, one- and two-unit properties can have a minimum down payment starting at 5% of the first $500,000 and 10% of the remainder.
Eligible three- and four-unit owner-occupied properties generally require at least 10% down.
Properties purchased entirely as investments are assessed differently, and some small-rental programs require at least 20% equity.
These distinctions are important because two properties with similar purchase prices may have different down-payment and qualification requirements.
Rental income can make a property more affordable, but becoming a landlord introduces additional responsibilities.
Consider a basement apartment generating $2,000 per month.
That sounds like $24,000 annually.
But what happens if the unit sits vacant for two months?
Or the furnace needs replacing?
Or the property requires unexpected repairs?
The actual financial benefit of the rental unit depends on more than the monthly rent.
I encourage buyers to account for vacancy, repairs, maintenance, insurance, utilities and potential tenant-related costs.
A property should ideally remain financially manageable even when rental income is temporarily interrupted.
Could this be a first-time homebuyer strategy?
Absolutely - provided the property and financing are appropriate.
For some first-time buyers, purchasing a home with a rental unit may provide a path into a neighbourhood or property type that would otherwise be difficult to afford.
For others, it may create an opportunity to begin building a real estate investment portfolio while occupying the property.
But I wouldn't automatically recommend purchasing the most expensive property a lender will approve.
The right question is whether the property makes financial sense after considering all its costs and responsibilities.
Buying a home with a rental unit can be an effective way to make homeownership more affordable.
But the financing deserves careful planning.
Rental-income treatment varies across lenders, property eligibility matters, and the amount of rent a lender recognizes can materially affect qualification.
Before making an offer, understand how the property will be financed - not just how much rent it might generate.
A well-structured mortgage can help turn a promising property into a sustainable long-term investment.
Ready to discuss your investment property goals and a Better Mortgage by Dom?
Call/text: 416 801-6616. Email: Domenic@BetterMortgagesByDom.ca
Connect/Follow me: Facebook, Instagram, X (formerly Twitter), LinkedIn
Download my app - featuring premium interactive tools, calculators, and illustrators for smart planning and real-time rate updates
Please share with anyone that you think can benefit from my help - all introductions are greatly appreciated!